 how-to
What to Do When Filing an Insurance Claim: 7 Steps
Table of Contents
- What to Do Immediately After an Incident
- How to Start Your Insurance Claim Filing Process
- Insurance Claim Documentation Checklist
- What Not to Say to Insurance Adjusters
- How Long Does an Insurance Claim Take?
- When a Claim Is Denied or Disputed
- How Claims Affect Future Premiums and Emotional Toll
- Frequently Asked Questions
Last Updated: September 16, 2026
What to Do Immediately After an Incident
The process of filing insurance claim paperwork starts long before you dial your insurer, and the first hour after an incident shapes everything that follows. The steps you take at the scene determine whether your claim moves smoothly or stalls for months.
Safety comes first, always. Move vehicles or people out of traffic when it is safe to do so, call 911 if anyone is injured, and do not leave the scene of a collision before it is legal to do so. Once everyone is secure, your job shifts to evidence collection.
At Fadaie Insurance Services, Inc., we have guided policyholders through claims since 2006, and the pattern is consistent: the people who document thoroughly at the scene spend far less time fighting over details later.
Secure the Scene and Get to Safety
Turn on hazard lights, set cones or flares if you carry them, and get yourself and passengers behind a barrier or off the roadway. If the incident involves a hazard like a gas leak or downed power line, keep everyone well clear and wait for emergency responders.
Do not admit fault, apologize, or speculate about what happened. Casual remarks at the scene can resurface during a liability investigation, even when you meant nothing by them.
Collect Contact and Witness Information
Exchange names, phone numbers, insurance company names, and policy numbers with the other party. Photograph their license plate and, where permitted, their driver's license.
Then look for witnesses. Bystanders leave within minutes, so approach them quickly and ask for a name and phone number. A witness statement gathered at the scene carries far more weight than one you track down three days later. If police respond, ask how to obtain a copy of the police report and note the responding officer's name and badge number.
How to Start Your Insurance Claim Filing Process
The process of filing insurance claim paperwork begins with one call, and what you do in that call sets the tone for the entire claim. Report the incident promptly, even if you are unsure whether you will file. Most policies require timely notice, and delay gives an insurer grounds to question the claim.
Gather your policy number, the incident details, and any documentation before you call. Then work through two things in order: getting your claim number, and understanding exactly what your policy covers.
Contact Your Insurer and Get a Claim Number
Call the claims line listed on your policy or use your insurer's app if it supports first notice of loss. You will speak with a claim representative who opens the file and assigns a claim number. Write that number down and use it on every piece of written correspondence from that point forward.
Ask the representative two questions before you hang up: who your assigned adjuster will be, and what the expected next step is. Independent agencies like Fadaie Insurance Services, Inc. can often help you reach the right claims contact faster and confirm your policy details are correct before you file.
Review Your Policy Coverage and Deductible
Pull out your declarations page and read it before you agree to anything. You need to know your deductible, your coverage limits, and whether the loss falls under collision, comprehensive, liability, or a property endorsement.
This is where the filing-versus-paying decision happens. If the repair estimate is close to your deductible, paying out of pocket may cost you less over time than a claim that raises your premium increase risk. Run the numbers honestly before you commit.
| Situation | File a Claim | Pay Out of Pocket |
|---|---|---|
| Damage well above deductible | Yes | No |
| Damage near or below deductible | Usually no | Yes |
| Third-party liability involved | Yes | Not an option |
| Minor cosmetic damage, no injury | Often no | Yes |
| Total loss or safety hazard | Yes | No |
Insurance Claim Documentation Checklist
Documentation is the single biggest factor in whether your claim settles quickly or drags. A complete file gives the adjuster nothing to question, which shortens claim processing time and reduces the chance of a claim denial over missing evidence.
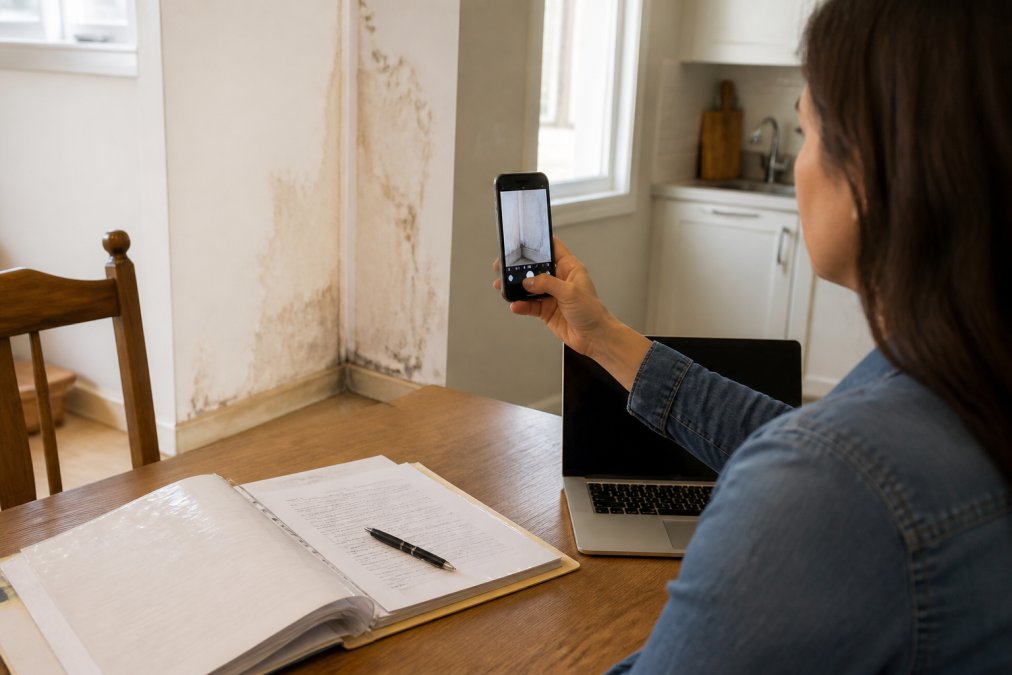
Work through this checklist before your adjuster visit:
- Photographs and video of all damage from multiple angles and distances
- A written incident report with date, time, location, and weather conditions
- Police report number or responding officer details, if applicable
- Names, phone numbers, and witness statement notes
- Contact and insurance details for every other party involved
- Repair estimates from at least two licensed contractors
- Receipts for any emergency repairs or temporary lodging
- A running log of every call, email, and letter with dates
Photographic Evidence and Repair Estimates
Photographic evidence should show context, not just close-ups. Take wide shots that establish where the damage sits, then move in for detail. Capture serial numbers on damaged appliances and date-stamp everything if your phone allows it.
What Not to Say to Insurance Adjusters
What not to say to insurance adjusters comes down to one principle: answer the question asked, and nothing more. Adjusters are trained to gather statements that limit the insurer's liability, and casual speculation can be used to reduce or deny your settlement. Maintaining this disciplined focus prevents you from inadvertently volunteering information that could complicate the process of dealing with adjusters, a critical skill to refine as you navigate the complexities of your claim.
Avoid these phrases entirely:
- "I think it was probably my fault." Never assign fault. That is the adjuster's determination to make.
- "It's not that bad." Downplaying damage gives the insurer a reason to cut your reimbursement.
- "I'm not sure, but maybe..." Guessing at timelines or causes creates contradictions later.
- "I already threw that away." Discarding damaged property before the adjuster inspects it can void that portion of the claim.
- "I don't need to file, I'll just handle it." Saying this and then filing weeks later invites a timeliness dispute.
How Long Does an Insurance Claim Take?
Most straightforward claims resolve in a matter of weeks, but the honest answer is that timelines vary widely by claim type, damage severity, and how complete your documentation is. A total loss with clear liability moves faster than a complex third-party liability dispute with contested facts.
What Slows Down Claim Processing Time
The most common delays are self-inflicted. Missing documentation, delayed reporting, and unanswered adjuster calls push your file to the bottom of the queue.
Other slowdowns come from the insurer's side:
- Adjuster scheduling backlogs after a regional catastrophe
- Underwriting review when coverage questions arise
- Subrogation proceedings when another party's insurer is pursued for recovery
- Appraisal when you and the insurer disagree on value
When a Claim Is Denied or Disputed
A claim denial is not the end of the process. Most denials cite a specific reason, and many are reversible when you respond with evidence.
If you believe the denial is wrong:
- Request the denial in writing with the specific policy language cited
- Submit a written rebuttal with your documentation attached
- Ask for a supervisor review or the insurer's internal appeals process
- Contact your state insurance department to file a complaint if the insurer will not engage
- Consult an attorney experienced in insurance disputes for large or complex losses
How Claims Affect Future Premiums and Emotional Toll
A filed claim can raise your premium at renewal, and how much depends on the claim type, your history, and the insurer's underwriting rules. Not all claims carry equal weight: an at-fault collision typically affects rates more than a comprehensive claim for storm damage or theft.
A few things genuinely help:
- Ask a trusted friend or family member to sit in on adjuster calls and take notes
- Keep one folder, physical or digital, for every document so nothing gets lost
- Set a weekly check-in with yourself to track progress instead of checking daily
- Lean on your agent for the parts that require policy expertise
Frequently Asked Questions
What not to say when filing an insurance claim?
Avoid admitting fault, guessing at values, or saying 'it was my fault' or 'I think it's about $5,000.' Never speculate about what happened or offer opinions on liability. Stick to facts: what you observed, when it happened, and what was damaged. If you're unsure how to answer a question from an insurance adjuster, it's fine to say you'll check your records and follow up in writing.
How do I claim insurance if it's not my fault?
File with your own insurer first, then let them pursue subrogation against the at-fault party's carrier. Get a police report and witness statements, which establish third-party liability. Your deductible may apply upfront, but your insurer typically reimburses it if subrogation succeeds. Keep all repair estimates and out-of-pocket expenses documented for reimbursement.
How long do I have to file an insurance claim after an incident?
Most policies require prompt notice, often within days to weeks, but the legal statute of limitations for filing suit varies by state. Property claims typically have shorter contractual deadlines than liability claims. Don't wait: late reporting is one of the most common reasons for claim denial. Contact your insurer as soon as you've secured the scene and documented the damage.
What's the biggest mistake people make when dealing with an insurance claim?
Accepting the first settlement offer without reviewing the adjuster's damage assessment or getting a second repair estimate. Policyholders often don't realize they can negotiate, request an appraisal, or dispute a claim denial. Keep written correspondence and a claim number handy, and don't sign a release until you're confident the settlement covers your actual losses.