 how-to
What Is Commercial Property Insurance for Restaurants?
Table of Contents
- What Commercial Property Insurance Covers for a Restaurant
- Restaurant Equipment Insurance: Protecting Kitchen Fixtures and Cooking Equipment
- Covered Perils: Fire, Wind, Theft, and Water Damage
- Restaurant Food Spoilage Insurance and Temperature-Control Losses
- Commercial Property Insurance vs General Liability: What's the Difference?
- Restaurant Business Interruption Insurance and Loss of Income
- How to Calculate Coverage Limits and Choose Replacement Cost vs Actual Cash Value
- How to File a Commercial Property Insurance Claim for Your Restaurant
- Frequently Asked Questions
Last Updated: October 15, 2026
What Commercial Property Insurance Covers for a Restaurant
Commercial property insurance is a policy that pays to repair or replace the physical assets your restaurant owns or leases when they are damaged by a covered event.
Restaurants carry more physical risk than most small businesses. A single overnight freezer failure can destroy thousands of dollars of inventory.
Most owners find out what their policy actually covers only after something breaks. That is the wrong time to learn.
Here is what we will cover:
- The property a restaurant policy protects, from the building to the dry goods
- The perils that trigger a payout, and the ones that never do
- How food spoilage and business interruption coverage work
- How to set limits and file a claim that gets paid
Buildings and Structures You Own or Lease
The building itself is the first piece of coverage. If you own the property, your policy should insure the structure, the roof, the exterior walls, and permanently attached fixtures.
If you lease, the landlord usually insures the building.
Check your lease before you set limits. Many commercial leases put repair obligations on the tenant for anything beyond the bare shell.
Business Personal Property, Contents, and Inventory
Business personal property coverage pays for the movable items inside your restaurant. That includes:
- Tables, chairs, booths, and bar stools
- Kitchen equipment and cooking equipment
- Smallwares, dishes, glassware, and utensils
- Inventory, raw ingredients, dry goods, and supplies
- Computers, point-of-sale systems, and office furniture
Covered property also extends to items you lease from a vendor, such as a coffee machine under contract. Read that vendor agreement closely, because the vendor may require you to carry the coverage.
Restaurant Equipment Insurance: Protecting Kitchen Fixtures and Cooking Equipment
Restaurant equipment insurance is the part of your property policy that protects the tools of your trade: ranges, ovens, fryers, grills, refrigerators, freezers, dish machines, and prep equipment.
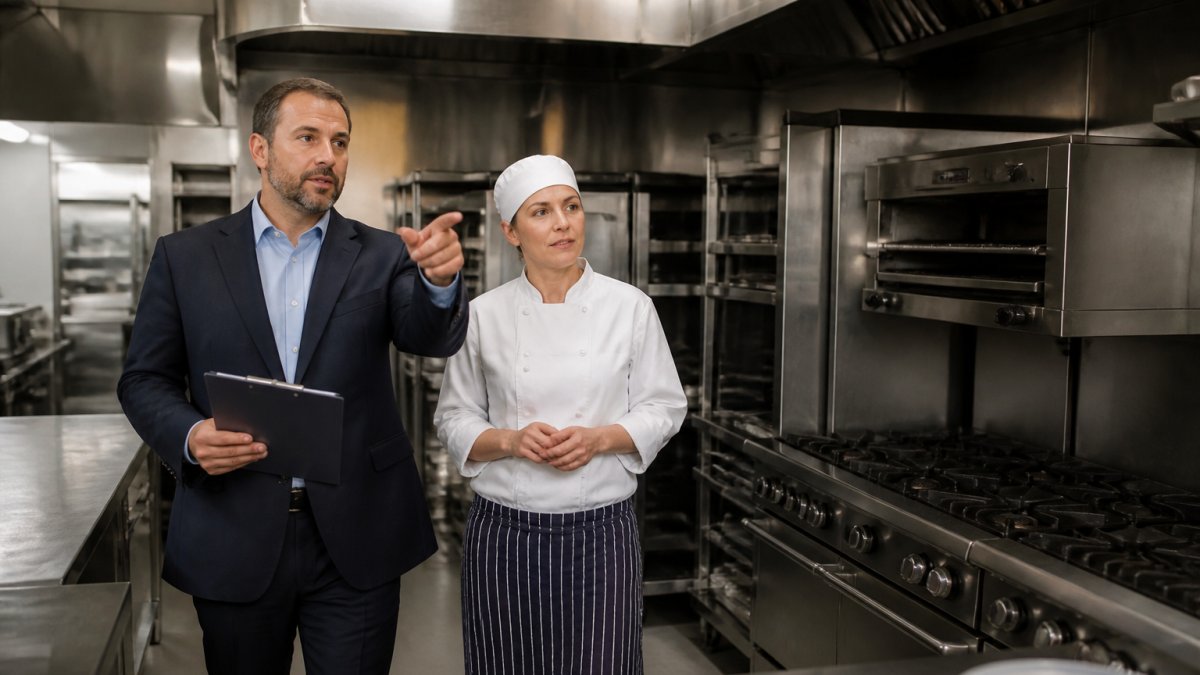
Two details trip owners up here. First, equipment that is permanently wired or plumbed counts as a fixture, not contents. Second, most policies cap coverage for outdoor equipment like smokers, generators, and patio heaters.
Covered Perils: Fire, Wind, Theft, and Water Damage
A covered peril is a specific event your policy agrees to pay for. Most commercial property policies are written on a broad form that covers a long list of perils, including:
- Fire damage and lightning
- Windstorm and hail
- Theft and vandalism
- Sprinkler leakage and water damage
- Building collapse
Natural disasters are handled differently. Flood almost never appears on a standard policy, and earthquake coverage is usually excluded or offered only as a separate endorsement. Both require a standalone policy or an added endorsement.
What Standard Policies Exclude
Standard policies exclude the events that cause the most restaurant losses. Common exclusions include:
- Flood and surface water
- Earth movement, including earthquake and sinkhole
- Wear and tear, rust, and corrosion
- Employee dishonesty, unless you add crime coverage
- Power failure originating off your premises
That last one matters more than owners expect. If a fire damages an older kitchen, the city may require you to rebuild to current code. Without an ordinance or law endorsement, that extra cost is yours.
Restaurant Food Spoilage Insurance and Temperature-Control Losses
Restaurant food spoilage insurance covers the value of food that goes bad because of a covered event, such as a power outage, a broken compressor, or a fire that forces you to shut down the walk-in. It is usually added as an endorsement to your property policy rather than sold on its own, and the endorsement is what turns a denied claim into a paid one.
Temperature-control losses are the most common restaurant claim that owners assume is covered and is not. Say a storm knocks out power for two days. Your freezer thaws, and you throw out the entire contents. Whether that food is covered depends on four things:
- Whether spoilage is endorsed onto your policy
- Whether the power failure was caused by a covered peril on your premises
- Whether the outage originated on or off your premises
- What spoilage sublimit you selected
On-Premises vs. Off-Premises Power Failure
This distinction decides most spoilage claims. If a fire damages your own electrical panel and the walk-in dies, that is an on-premises event tied to a covered peril, and spoilage coverage is far more likely to respond.
Ask your agent one direct question: if the power goes out because of a grid failure and I lose my inventory, does this policy pay? Get the answer in writing.
Equipment Breakdown Is a Separate Coverage
A compressor that fails from old age is mechanical breakdown, not a covered peril under a standard property policy. Wear and tear is excluded. Equipment breakdown coverage, sometimes written as boiler and machinery coverage, is what pays when a refrigeration unit dies on its own rather than from a fire or storm. Pair it with spoilage coverage, because breakdown coverage repairs the equipment and spoilage coverage replaces the food.
Spoilage Sublimits and How They Are Set
Spoilage is almost always capped by a sublimit, and the cap is often far below the value of a full walk-in and freezer inventory. A restaurant holding $30,000 in protein, dairy, and produce at any given time may carry a $10,000 spoilage sublimit without realizing it. Set the sublimit against your peak inventory, not your average, because losses tend to happen when the walk-in is fullest.
What the Adjuster Will Ask For
An adjuster will not accept a round number. To prove a spoilage loss you need records that show what you had on hand and what it was worth:
- Purchase invoices or supplier statements for the weeks before the loss
- Inventory counts, even a simple weekly spreadsheet
- Photos of the walk-in or freezer contents
- A written list of discarded items with quantities and unit costs
- Proof of disposal, such as a dumpster photo or a waste hauler receipt
"About four thousand dollars" will not hold up. A dated inventory sheet with line items will.
Commercial Property Insurance vs General Liability: What's the Difference?
Commercial property insurance vs general liability comes down to one question: did something happen to your stuff, or to someone else? Property insurance pays to repair or replace your building, equipment, and inventory after a covered event.
The two coverages never overlap. A grease fire that destroys your kitchen is a property claim. Most restaurants need both, which is why a business owners policy bundles them.
| Coverage | What It Pays For | Typical Trigger |
|---|---|---|
| Commercial property | Building, equipment, contents, inventory | Fire, wind, theft, water damage |
| General liability | Third-party injury and property damage | Slip and fall, foodborne illness |
| Business interruption | Lost income while closed | Covered property damage |
| Workers' compensation | Employee injuries on the job | Staff hurt at work |
Restaurant Business Interruption Insurance and Loss of Income
Two details decide how much this coverage is worth to you.
Waiting periods. Many policies include a waiting period, often 72 hours, before loss of income benefits begin.
The period of restoration. Benefits run until you could reasonably reopen, not until you actually do.
A realistic scenario: a kitchen fire closes your dining room for six weeks. Property coverage rebuilds the kitchen.
How to Calculate Coverage Limits and Choose Replacement Cost vs Actual Cash Value
Replacement cost pays to rebuild or replace property at today's prices, with no deduction for age. Actual cash value pays replacement cost minus depreciation, so a ten-year-old oven pays out a fraction of what a new one costs.
To set your contents limit, build the number from the ground up:
- List every piece of kitchen and cooking equipment with its purchase price
- Add furniture, fixtures, smallwares, and point-of-sale gear
- Add the average value of inventory you hold at any time
- Add leasehold improvements you paid for
- Add signage, patio furniture, and outdoor equipment
For the building, use a professional valuation or a contractor's estimate rather than your purchase price. Market value and rebuild cost are different numbers, and after a total loss you need the rebuild number.
How to File a Commercial Property Insurance Claim for Your Restaurant
Filing a commercial property insurance claim for your restaurant starts with safety, then documentation, then a phone call. The order matters, because a claim without evidence is a claim you argue about later.
- Secure the site. Shut off gas and power, board up openings, and stop further damage. Most policies require you to prevent additional loss.
- Document everything. Photograph and video the damage before you clean up. Keep damaged items until the adjuster says you can toss them.
- Report the claim promptly. Call your agent the same day. Late reporting is one of the most common reasons claims get disputed.
- Keep your receipts. Save every expense tied to the loss, including emergency repairs, temporary storage, and replacement inventory.
- Track your lost income. Log closed days, canceled reservations, and reduced covers so your business interruption claim has numbers behind it.
- Review the settlement. Compare the adjuster's estimate to your own documentation before you accept. You can question line items you believe are wrong.
At Fadaie Insurance Services, Inc., our licensed advisors help business owners review their limits before a loss and walk them through the claims process after one. We work with businesses of every size, and we check for the gaps that standard policies leave open.
Frequently Asked Questions
Does commercial property insurance cover kitchen equipment and fixtures?
Yes, restaurant equipment insurance typically covers owned kitchen equipment such as ovens, refrigerators, fryers, and prep tables, along with attached fixtures like walk-in coolers and built-in shelving. Business personal property coverage handles items you own and use in the business, whether you lease or own the space. Check your policy limits for high-value items like commercial hood systems, since some policies cap coverage on specific equipment categories.
Does commercial property insurance cover food spoilage?
Standard commercial property policies often exclude food spoilage unless you add an endorsement. Restaurant food spoilage insurance covers inventory losses from refrigeration breakdowns, power outages, or equipment failure. Without this coverage, a walk-in cooler failing overnight could cost thousands in lost ingredients with no reimbursement. Ask your agent whether spoilage coverage is included or needs to be added separately.
How is commercial property insurance different from general liability?
Commercial property insurance vs general liability covers two separate risks. Property insurance pays to repair or replace your building, equipment, and inventory after a covered loss like fire or theft. General liability covers third-party claims, such as a customer slipping on a wet floor or a delivery driver damaging someone else's property. Most restaurants need both policies working together to close coverage gaps.
How much commercial property insurance does a restaurant need?
Your coverage limit should reflect the full replacement cost of your building (if owned), kitchen equipment, furniture, inventory, and leasehold improvements. Replacement cost coverage pays to rebuild or replace at today's prices, while actual cash value deducts depreciation. A licensed agent can help you calculate accurate limits so you are not underinsured after a major loss.
A restaurant fire, a burst pipe, or a two-day power outage can wipe out a year of work in an afternoon. The right policy puts the money back before the damage spreads to your finances. Fadaie Insurance Services, Inc. offers personalized guidance, competitive pricing, and support from licensed advisors who stay with you from the first quote through the final claim. Contact us today to review your commercial property coverage and close the gaps before you need them.